How to Choose a SEBI Investment Adviser
By Abhishek Kumar · Last Updated Date: 20-10-2026
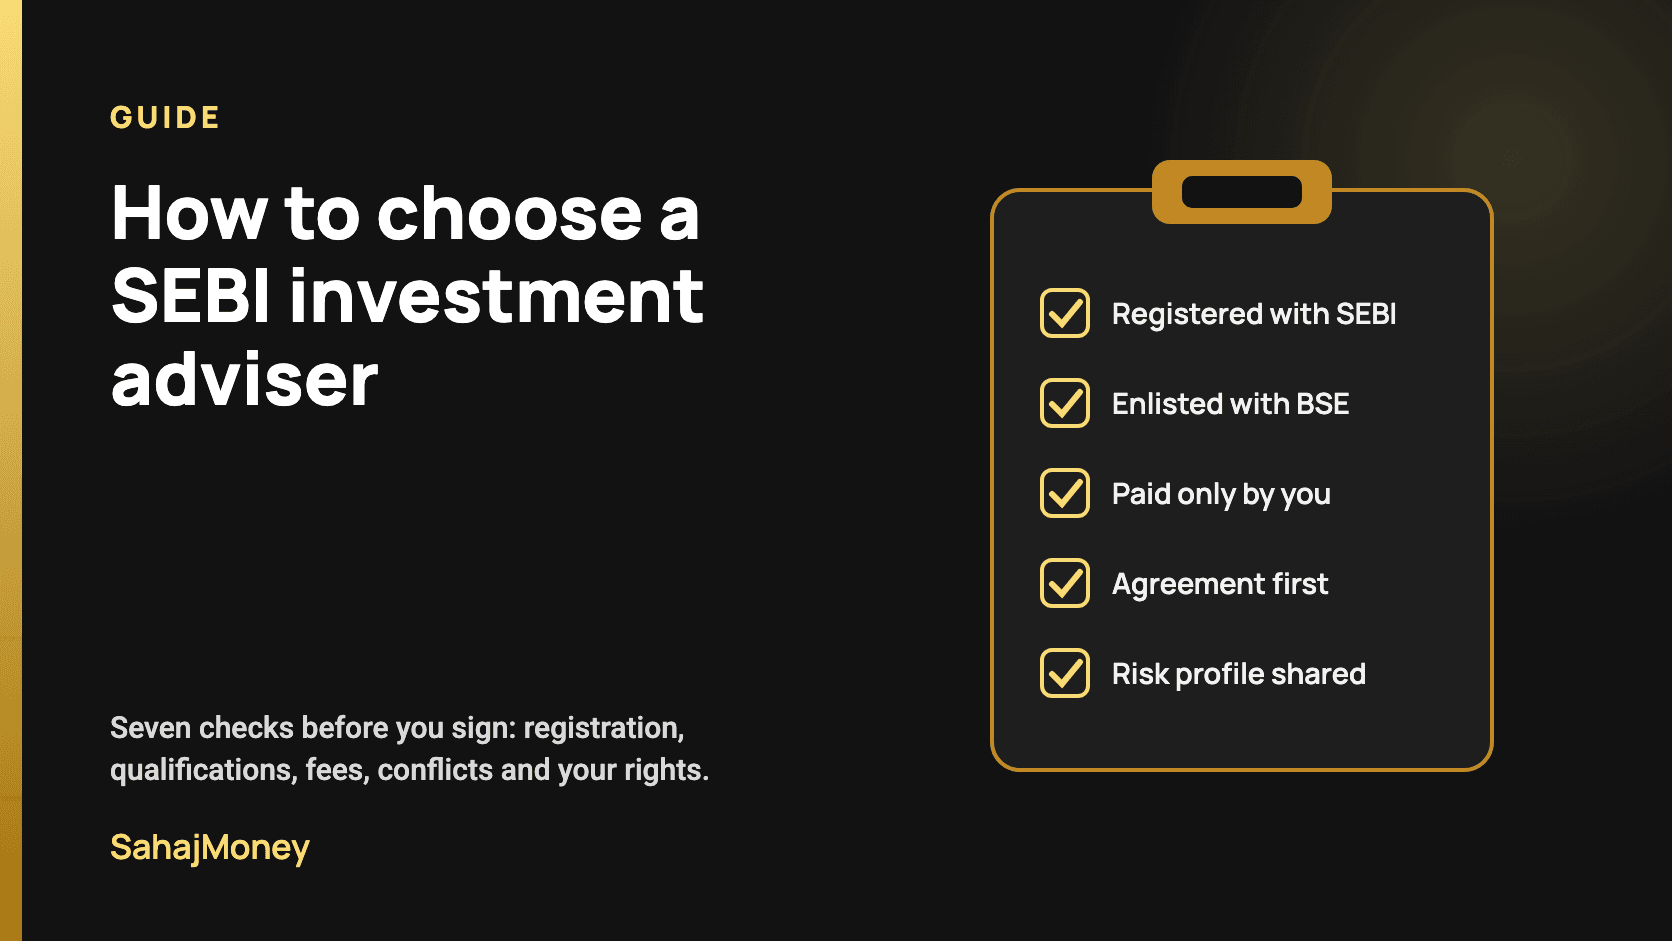
In short: check that the adviser is on SEBI's register and enlisted with BSE, holds the required NISM certificates, is paid only by you, does not also sell you products, and gives you a written agreement before taking any fee. Then make sure your risk profile is done and shared with you before any advice.
1. Check the registration
Anyone in the business of giving advice on securities for a fee in India must, with a few exemptions, be registered with SEBI as an Investment Adviser (RIA). A registration number starts with INA.
- Search the adviser's name or number on SEBI's list of registered investment advisers.
- Check that they are enlisted with BSE, which SEBI has recognised as the supervisory body for advisers (IAASB), on BSE's list of investment advisers.
- Make sure the name on the register matches the person or firm you will sign with.
Since 2024, SEBI-regulated entities and their agents may not associate with anyone who gives advice on securities without SEBI registration, or makes claims about returns or performance without SEBI's permission. Social media advice from someone not on the register is not regulated advice, however confident it sounds.
2. Check the qualifications
Since 25 November 2025, an individual adviser needs a graduate degree (or the CFA Charter) plus SEBI-specified NISM certification, or a NISM post-graduate programme. Those who give advice normally hold NISM Series X-A and X-B (advisers who qualified through the NISM post-graduate programme are exempt from these exams but must renew within three years), and certification must be renewed before it lapses. Ask which certificates the adviser holds and when they were renewed.
3. Understand how they are paid
A registered adviser is paid by you, in one of two ways:
| Fee mode | What you pay | SEBI's limit per family per year |
|---|---|---|
| Fixed fee | A set amount for the service | ₹1,51,000 |
| Assets under advice | A percentage of the investments advised on | 2.5% |
The limits come from SEBI's Master Circular for Investment Advisers (February 2026) and apply to individual and HUF clients, for advice on SEBI-regulated securities. They exclude statutory charges such as GST, and are upper limits, not prices. An adviser must recommend direct plans where they exist and may not take commission from product providers. Our guide to financial planner fees in India shows how to compare quotes.
4. Check that they don't also sell
An individual adviser may not provide distribution services, and their spouse, children and parents may not sell products to the adviser's clients. A firm that both advises and distributes must keep the two apart, client by client: you can receive advice or distribution from the group, not both. Ask directly whether anyone connected to the adviser earns anything from what you buy.
5. Read the agreement before you pay
- No advice and no fee before you sign an agreement. It must include the Most Important Terms and Conditions (MITC), which set out the fee, the service and your rights.
- No free trials and no part payments: SEBI does not allow them.
- No cash: fees are paid by bank transfer, cheque or UPI.
- Advance fees are limited to one year. If the service ends early, the unexpired fee is refunded, less a breakage fee of at most one quarter's fee.
- Apart from its fee, an adviser may not accept your money or securities. You keep your investments in your own accounts.
6. Expect a risk profile before any advice
An adviser must assess your risk profile, share it with you and get your consent to it before giving advice, and must make sure every recommendation suits that profile. SEBI's Investor Charter for advisers lists a right to suitability. If an adviser recommends products before asking about your finances, treat that as a warning sign.
7. Check the scope and the fit
Ask what the advice covers: only mutual funds, or a full plan including insurance, loans and tax. SEBI's rules cover advice on securities; for products outside SEBI's purview, such as insurance, the adviser must tell you so and take your declaration that SEBI offers no recourse for them. Ask how you will meet (video, phone, in person), how quickly they reply, and how often they review your plan.
Red flags
| You see | Why it matters |
|---|---|
| Not on SEBI's register, or no INA number shown | The advice is unregulated |
| A promise of fixed or certain returns | SEBI prohibits such claims |
| A free trial or part payment first | SEBI does not allow either |
| A request to send investment money to the adviser, to trade without your consent on each trade, or for your logins or OTPs | Advisers may not hold client funds or securities, need your consent for every trade, and must never ask for logins or OTPs |
| Regular plans recommended where a direct plan exists | Advisers must recommend direct plans |
| No written agreement | No advice or fee is allowed before one |
Questions to ask on the first call
- What is your SEBI registration number, and are you enlisted with BSE?
- Which NISM certificates do you hold?
- What exactly do I pay, in which fee mode, and what does it include?
- Does anyone connected to you earn from the products you recommend?
- Who will prepare and review my plan, and how often?
- How do I raise a complaint if I'm unhappy?
If something goes wrong
Complain to the adviser first; they must resolve it within 21 days. If that doesn't work, file on SEBI's SCORES platform within one year. The adviser must answer there within 21 days; if you are still unhappy, you can ask for a review by BSE (the IAASB), and then by SEBI. Unresolved disputes can go to conciliation and arbitration on the market's online dispute resolution portal, SMART ODR.
About SahajMoney
SahajMoney is the advisory practice of Abhishek Kumar, an individual SEBI Registered Investment Adviser (INA100008045), enlisted with BSE Limited (IAASB), enlistment number 1686. We charge a fixed fee of ₹15,000 for the first year and ₹7,500 a year to renew, both including GST, per couple, and earn nothing from any product. Read what a fee-only planner does or see our services.
Registration granted by SEBI, enlistment with IAASB and certification from NISM in no way guarantee performance of the IA or provide any assurance of returns to investors.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.


More of Abhishek's views on money management
You may also like
Are Private Banking Fees Negotiable in India?
Private banking and wealth fees in India: which are negotiable, which are set by rules, SEBI's limits, and how they compare with fee-only advice.
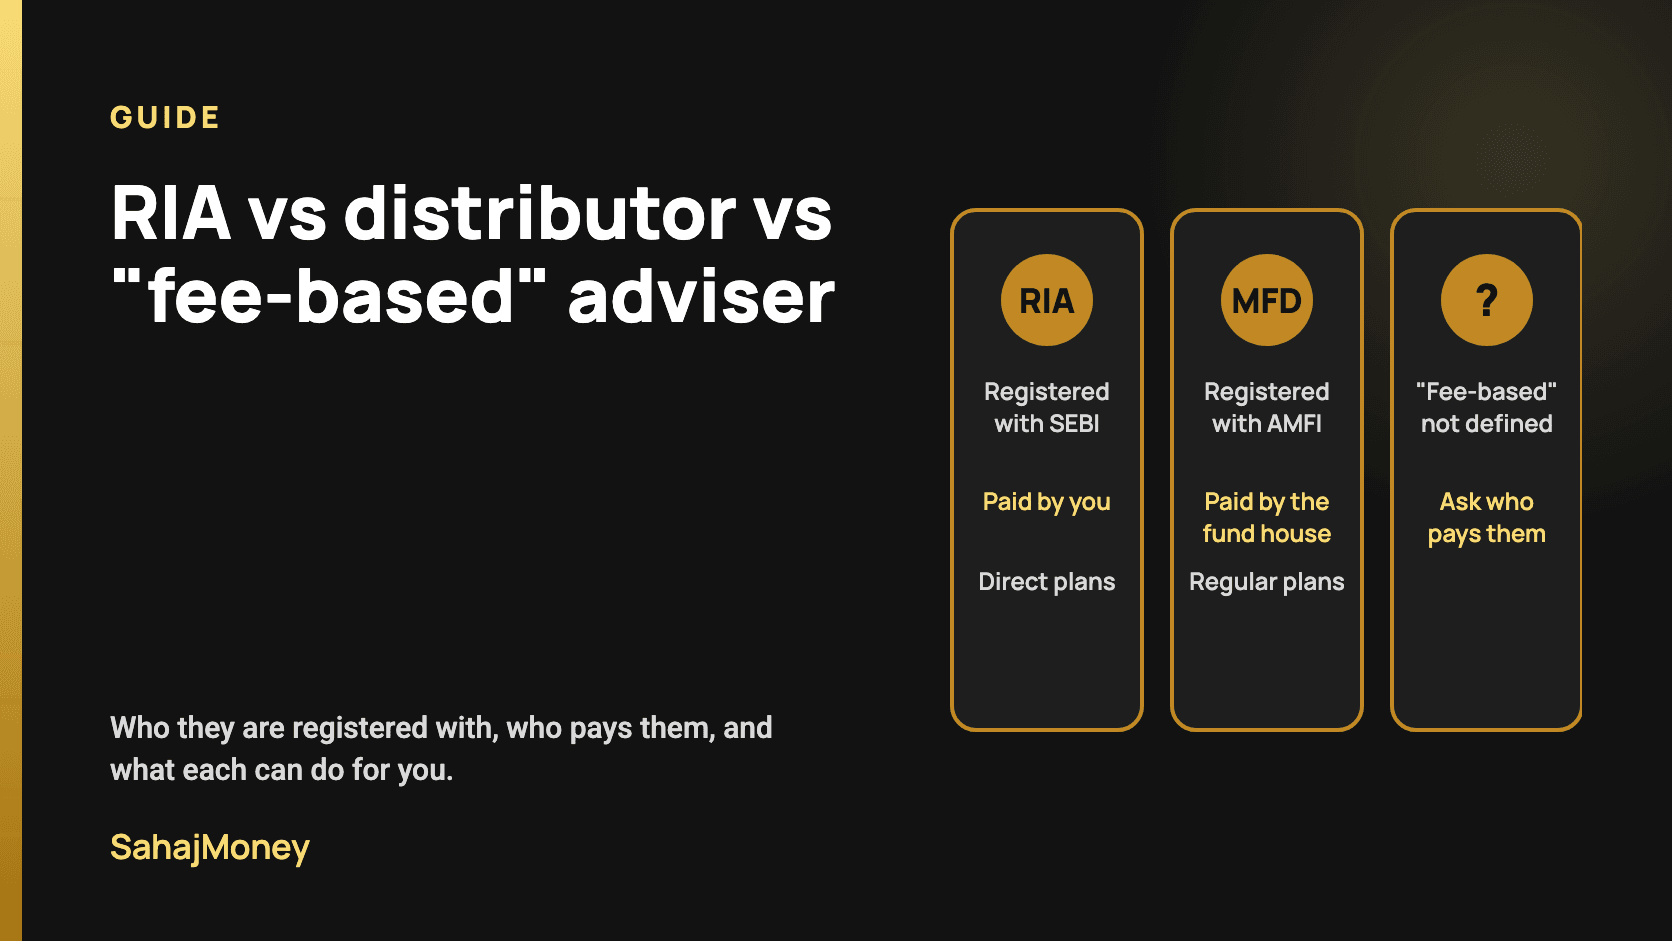
RIA vs Distributor vs Fee-Based Adviser
How SEBI Registered Investment Advisers, mutual fund distributors and "fee-based" advisers differ: registration, who pays them, and what each can do.
Senior Citizens' Savings Scheme (SCSS) Guide
SCSS explained: who can invest, the ₹30 lakh limit, 8.2% for Oct–Dec 2026, quarterly interest, tax, unlimited 3-year extensions and early exit.
Tailored Financial Advice At a Price You Can Afford!
Speak to SahajMoney® advisor today to achieve your financial goals with confidence.