RIA vs Distributor vs Fee-Based Adviser
By Abhishek Kumar · Last Updated Date: 17-10-2026
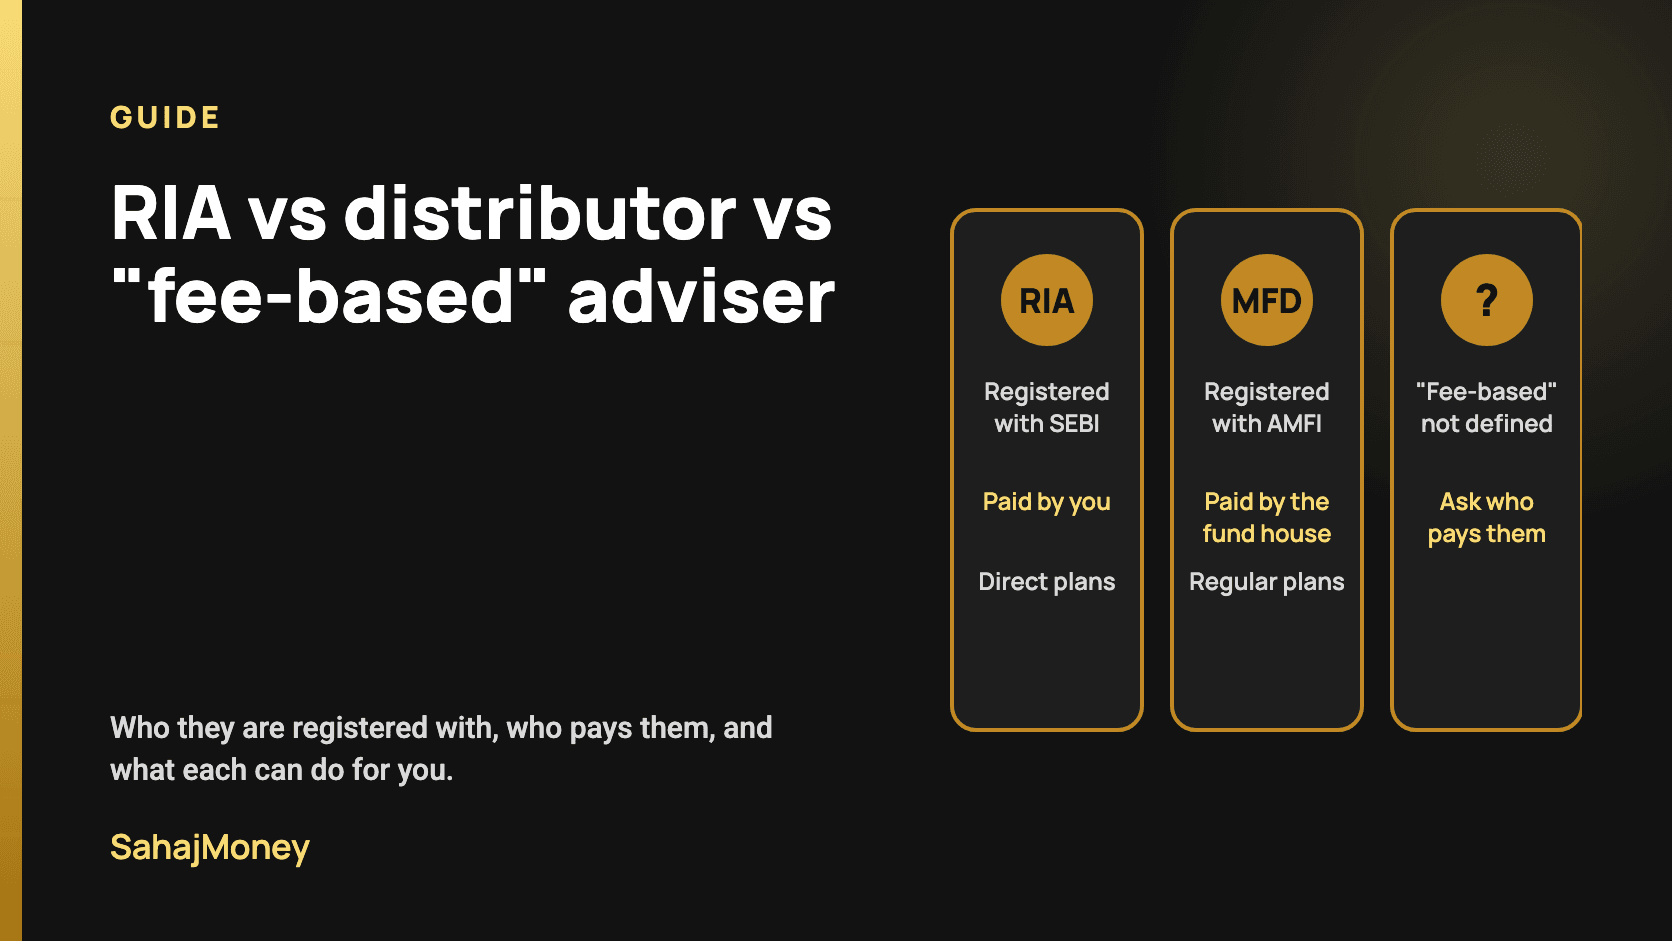
In short: a SEBI Registered Investment Adviser (RIA) is paid by you and gives advice. A mutual fund distributor (MFD) is registered with AMFI, is paid commission by the fund house, and helps you invest in mutual funds. "Fee-based" is not a category in SEBI's rules; ask exactly who pays the person and how. Each serves a different need, and knowing which one you are dealing with helps you judge the advice.
The three side by side
| SEBI Registered Investment Adviser | Mutual fund distributor | "Fee-based" adviser | |
|---|---|---|---|
| Registered with | SEBI (number starts INA), enlisted with BSE | AMFI (ARN number); each salesperson has an EUIN | Not a SEBI category: check what registration they hold |
| Who pays them | You, a fixed fee or a percentage of assets advised | The fund house, as commission | Depends: ask whether fees, commission or both |
| Mutual fund plans | Direct plans | Regular plans | Depends on the registration |
| Scope | Advice and financial planning | Selling mutual funds, with advice incidental to that | Depends on the registration |
SEBI Registered Investment Adviser
An RIA gives investment advice, including financial planning, for a fee paid by the client. For individual and HUF clients, SEBI caps the fee for advice on SEBI-regulated securities at ₹1,51,000 a year per family in fixed-fee mode, or 2.5% a year of the assets advised on, excluding statutory charges such as GST. An RIA must recommend direct plans where available, may not take commission, and, if an individual, may not distribute products. You can check the registration on SEBI's list of investment advisers.
Mutual fund distributor
A distributor holds an ARN from AMFI after passing a NISM certification (Series V-A, or the newer V-D), and follows AMFI's code of conduct. Distributors are paid trail commission by the fund house out of the scheme's expenses, which is why regular plans have a higher expense ratio than direct plans of the same scheme. Your consolidated account statement shows the commission paid on your investments every half-year.
A distributor may give advice only incidental to selling mutual funds. SEBI does not allow distributors to call themselves "Independent Financial Adviser", "IFA" or "Wealth Adviser"; AMFI requires them to display the tagline "AMFI-registered Mutual Fund Distributor" with their name and ARN. Many investors value a distributor's help with paperwork, transactions and service, and pay for it through the commission. You can check a distributor on AMFI's distributor search.
"Fee-based" adviser
Neither SEBI's adviser rules nor AMFI's rules define "fee-based". People use it for different arrangements: some charge only a fee, others charge a fee and also earn commission. An individual RIA cannot do both, and a firm that does both must keep advice and distribution with separate clients. So when someone describes themselves as fee-based, ask:
- Are you registered with SEBI as an investment adviser, with AMFI as a distributor, or both?
- Will I pay you a fee, will a product provider pay you, or both?
- Will you recommend direct plans or regular plans?
Other titles you may see
- Research analyst: registered with SEBI to publish research and buy, sell or hold recommendations on securities, rather than advice for your overall situation.
- Insurance agent or broker: works under IRDAI's rules (agents are appointed by an insurer; brokers are registered with IRDAI) and is paid commission or remuneration by insurers. SEBI's rules don't cover insurance.
Which one do you need?
If you want help deciding what to do with your money (how much to save, how to invest for each goal, how much insurance to hold), you are looking for advice; for advice on securities such as mutual funds and shares, an RIA is the registered route. If you have already decided and want help buying and servicing mutual funds, a distributor provides that. Whichever you choose, check the registration and ask how the person is paid.
About SahajMoney
SahajMoney is the advisory practice of Abhishek Kumar, an individual SEBI Registered Investment Adviser (INA100008045), enlisted with BSE Limited (IAASB), enlistment number 1686. We are paid only by our clients, a fixed fee of ₹15,000 for the first year and ₹7,500 a year to renew, both including GST, per couple, and recommend direct plans. Read how to choose a SEBI investment adviser.
Registration granted by SEBI, enlistment with IAASB and certification from NISM in no way guarantee performance of the IA or provide any assurance of returns to investors.
Investment in securities market are subject to market risks. Read all the related documents carefully before investing.


More of Abhishek's views on money management
You may also like
Are Private Banking Fees Negotiable in India?
Private banking and wealth fees in India: which are negotiable, which are set by rules, SEBI's limits, and how they compare with fee-only advice.
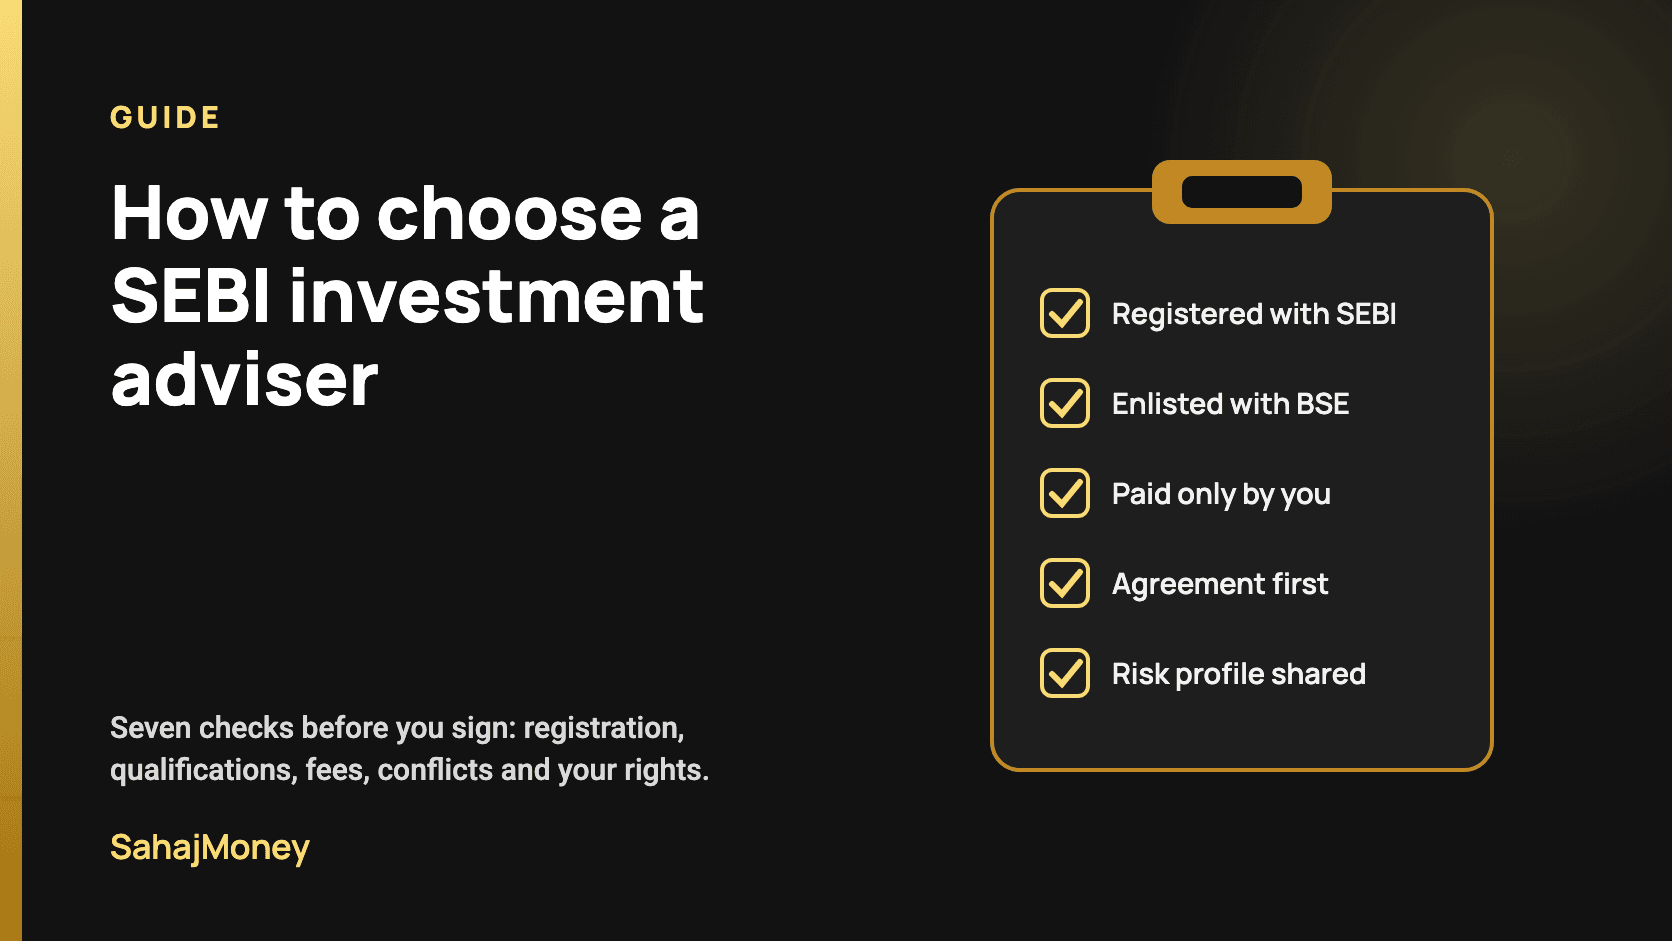
How to Choose a SEBI Investment Adviser
Seven checks before you hire a SEBI Registered Investment Adviser: registration, qualifications, fees, conflicts, the agreement and your rights.
Senior Citizens' Savings Scheme (SCSS) Guide
SCSS explained: who can invest, the ₹30 lakh limit, 8.2% for Oct–Dec 2026, quarterly interest, tax, unlimited 3-year extensions and early exit.
Tailored Financial Advice At a Price You Can Afford!
Speak to SahajMoney® advisor today to achieve your financial goals with confidence.